Centrelink Loans: What You Can Actually Get, and What It Really Costs
Key takeaways
- You can get a loan while receiving Centrelink payments, as licensed lenders are allowed to count eligible Centrelink income; being on benefits does not automatically rule you out.
- A Centrelink Advance Payment from Services Australia is interest-free (you repay only what you borrow from your future payments) and a No Interest Loan (NILS) from Good Shepherd charges no interest and no fees for essential items, making these the cheapest Centrelink loan options.
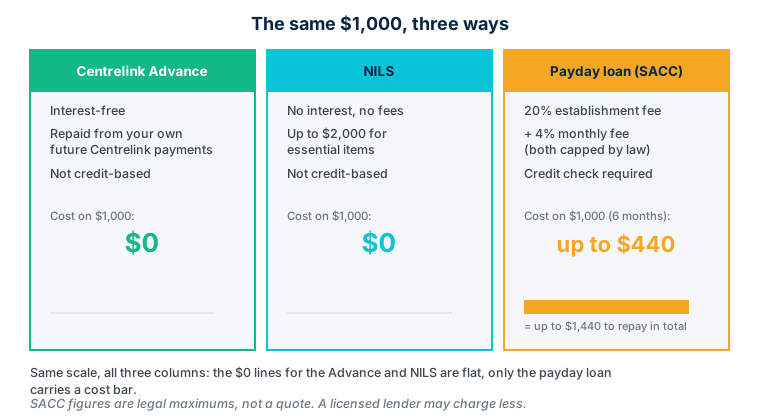
- A payday loan (Small Amount Credit Contract) is the most expensive option on this list: Australian law caps the cost at a maximum establishment fee of 20% of the amount borrowed plus a maximum monthly fee of 4%, where an interest-free Centrelink Advance Payment or a No Interest Loan costs nothing in fees at all.
- No legitimate lender offers guaranteed approval or no credit check. Licensed lenders are legally required to assess affordability under responsible-lending law, and a panel of licensed lenders assesses each application and sets any rate.
- Free alternatives that often beat a loan include the National Debt Helpline (1800 007 007) and Services Australia crisis or special payments you may not have to repay.
Quick honesty note. Perfect Payday is not a lender and is not Centrelink. It’s a trading name of Tiny Ventures (ABN 52 168 226 480), Credit Representative No. 516845, a credit referral service. When you apply, we may pass your details to a panel of licensed lenders who assess your application and set any rate; we don’t decide that, and we may receive a fee if you proceed. We’ve written this page to help you find the cheapest option for your situation, even when that isn’t us.
Yes, you can get a loan while receiving Centrelink payments. Lenders are allowed to count eligible Centrelink income, so being on benefits doesn’t automatically rule you out. But you have more options than a payday loan, and some cost nothing. This page walks through all of them, in order of cost, so you can start with the cheapest and only move down the list if you have to.
Compare your options at a glance
| Option | Typical amount | Interest / fees | How fast | Credit check? |
|---|---|---|---|---|
| Centrelink Advance Payment | Varies by payment & circumstances | Interest-free: repay only what you borrow | A few business days | No |
| No Interest Loan (NILS) | Up to $2,000 (up to $3,000 bond / $5,000 car) | No interest, no fees | ~1–2 weeks | No |
| Payday loan (SACC) | $300–$2,000 | 20% establishment + 4%/month (capped by law) | Same day–48 hrs | Yes |
Sources: Services Australia, Good Shepherd NILS, ASIC Moneysmart. Figures current as of June 2026; check the official pages for the latest.
Can you actually “borrow from Centrelink”?
Not in the way the term suggests. Centrelink (run by Services Australia) doesn’t offer general-purpose loans. What it does offer is an Advance Payment: you get part of your future Centrelink payment early, then it’s deducted from your regular payments over the following fortnights. It’s interest-free, so you pay back exactly what you took, nothing more.
- Who’s eligible: people on payments such as Age Pension, JobSeeker, Disability Support Pension, Carer Payment, Parenting Payment, Youth Allowance and Family Tax Benefit Part A, usually after about three months on the payment.
- How much: depends on your payment type and circumstances. See the official Services Australia advance payments page.
- How to apply: through myGov, the Express Plus Centrelink app, or by phone.
This is almost always the cheapest way to bring forward money you’re already going to receive.
No Interest Loans (NILS): the genuine “loan on Centrelink”
For an essential item (a fridge, car repairs, a laptop for study, medical or dental costs) the No Interest Loan Scheme, run by Good Shepherd through 170+ community organisations, is usually the best loan you can get.
- Borrow up to $2,000 for essentials, up to $3,000 for a rental bond or disaster recovery, or up to $5,000 for an essential vehicle.
- Cost: nothing beyond the amount you borrow, with no interest and no fees.
- Eligible if you have a Health Care Card or Pensioner Concession Card, or earn under $70,000 a year ($100,000 for couples/people with dependants).
- Find a provider: call 13 NILS (13 6457) or use the Good Shepherd NILS locator.
Payday loans (SACCs) on Centrelink: how they work and what they cost
A “payday loan” is legally a Small Amount Credit Contract (SACC): up to $2,000, repaid over 16 days to 12 months. Licensed lenders can count Centrelink payments as income, so being on benefits doesn’t automatically rule you out. But this is the most expensive option here.
By law, a SACC lender can only charge an establishment fee of up to 20% of the amount borrowed plus a monthly fee of up to 4%.
How that compares with your cheaper options
Those caps are the legal ceiling, not a quote, and the licensed lender who assesses you sets the actual figure inside them. Put the three routes side by side and the ranking answers itself: a Centrelink Advance Payment costs nothing beyond the money you bring forward, a NILS loan for an essential item charges no interest and no fees, and a SACC adds a capped setup charge plus a capped fee for every month you hold it. That gap is exactly why payday loans sit last on the list above. If you want the maximum for a specific sum, put your own amount and term into the cost calculator.
The protected-earnings rule (this one protects you): by law a lender generally can’t sign you up to a SACC if your total SACC repayments would exceed 10% of your net income. If a lender ignores that, it’s a red flag, and grounds for an AFCA complaint.
Which Centrelink payments do lenders accept?
This is the question most pages skip, and it decides more applications than a credit score does. Lenders don’t treat “Centrelink income” as one thing. They sort payments by how stable they are, and the pattern across the lenders whose criteria we’ve read is consistent enough to set out plainly.
| Payment | How lenders usually treat it | Why |
|---|---|---|
| Age Pension, Disability Support Pension, Carer Payment, Service Pension | Widely accepted, often as your main income | Long-term payments that don’t change with study or job status |
| Parenting Payment, Family Tax Benefit | Usually counted, often alongside other income | Regular, but lenders check whether it covers the repayment on its own |
| JobSeeker | Counted by some lenders, rarely enough by itself | Modest and expected to end when you find work |
| Youth Allowance, Austudy, ABSTUDY | Frequently excluded outright | Tied to study or age, so lenders treat it as short-lived; Money3, for one, publishes that it can’t consider these |
That’s a description of how the market behaves, not a promise about any lender. Every application still comes down to whether the repayments fit your budget under responsible-lending law. Our eligibility guide walks through the full checklist.
The 50% rule most lenders apply
The single most common criterion, and the one that surprises people, is a cap on how much of your income can come from Centrelink. Cash Converters publishes it as “less than 50% from Centrelink”. Nimble’s small-loan pages say you must be employed with no more than 50% of your income from government benefits. MoneySpot’s Target Market Determination says approval on sole Centrelink income is “unlikely”. The rule isn’t universal, and some lenders do lend to people whose only income is a pension, but if Centrelink is all or most of what comes in, expect the pool of lenders who’ll consider you to shrink sharply.
What that means in practice
If your income is entirely Centrelink, the honest reading of the market is that a payday loan is both the hardest option to get and the most expensive one you could be approved for. That’s exactly the situation the Advance Payment and NILS exist for, and it’s why they sit above any loan on this page. If you also have part-time wages, the picture opens up, and the pay-advance apps become a possibility too, though most of them exclude anyone earning more than about half their income from benefits; our pay advance apps guide has the specifics.
How to apply for a Centrelink Advance Payment
Because it’s interest-free, this is the first thing to check, and it’s quicker than most people expect.
Step by step
- Sign in to myGov and go to your Centrelink online account, or open the Express Plus Centrelink app.
- Choose Apply for advance. The screen shows whether you’re eligible and the amount you can take, which depends on your payment type.
- Pick the amount and confirm. Repayments are deducted automatically from your regular payments, usually spread over the following 13 fortnights.
- The money generally arrives in your bank account within a few business days.
Things to know before you tap confirm
- You usually need to have been on your payment for about three months.
- Because repayments come off your future payments, each fortnight will be smaller until it’s cleared. Work out whether the reduced amount still covers rent and bills.
- Family Tax Benefit Part A has its own advance rules and amounts.
- If you’d rather talk it through, call Services Australia on the number for your payment, or check the official advance payments page.
What a lender looks at when you’re on Centrelink
If you do apply for a SACC, knowing what the lender will check saves you a decline on your file.
Ninety days of bank statements
Licensed lenders read your recent transactions, not just your credit score. They’re looking for your Centrelink payments arriving on schedule, how much is left after rent and bills, and any dishonoured direct debits. Two or three dishonours in the last 90 days will weigh more heavily than an old default.
Other small loans in the last 90 days
The law presumes a new SACC is unsuitable if you’ve had two or more small loans in the past 90 days, or you’re behind on one now. A lender can rebut that, but most won’t. If that’s your position, the answer is a hardship conversation, not a third loan; our financial hardship page explains your rights.
The protected-earnings rule
A lender generally can’t put you into a SACC if your total SACC repayments would come to more than 10% of your net income. On a pension, that ceiling arrives quickly, which is one reason approvals for larger amounts are rare on Centrelink alone.
Your credit file
Bad credit isn’t a bar on its own, because affordability is the test. But a lender will still look, and anyone advertising “no credit check” isn’t a licensed lender following the rules. Our loans for bad credit page covers how the file is read.
Centrelink loans for your situation
The rules are the same whatever payment you receive (a licensed lender must check the loan is affordable, and the cheaper options above usually win), but the practical picture differs a little by situation:
- Single parents (Parenting Payment). Parenting Payment is regular income that many lenders will count, so being a single parent on Centrelink doesn’t rule you out. For one-off essentials like a fridge, car repair or back-to-school costs, a Centrelink Advance or a No Interest Loan is almost always cheaper than a payday loan, and Parenting Payment recipients are squarely eligible for both.
- Students (Youth Allowance, Austudy, ABSTUDY). Student incomes are low, which makes affordability tight and a SACC an expensive way to cover a laptop or textbooks. A NILS loan for study essentials, plus your university or TAFE student support and hardship funds, will usually serve you far better than a short-term loan.
- Age Pension and Disability Support Pension. Pension income is accepted by many lenders, and pensioners can draw a Centrelink Advance. We cover this in detail on our pensioner loans page.
- JobSeeker and Youth Allowance (job seekers). These payments can count as income, but they’re modest, so a lender’s affordability check is the real hurdle, not your benefit type. Treat any “guaranteed approval for JobSeeker” claim as a warning sign.
- Carer Payment and Family Tax Benefit. Often accepted as part of your income picture. If you’re stretched by caring costs, a financial counsellor can help you find grants and concessions you may be missing.
Whatever your payment, if a shortfall is from a one-off bill rather than an ongoing gap, start with a Centrelink Advance or NILS, and if money is genuinely tight, our financial hardship options and free counselling below come first.
Before you borrow: free help that often beats a loan
- National Debt Helpline, 1800 007 007. Free, confidential financial counsellors (not salespeople).
- Services Australia crisis/special payments: you may qualify for one-off help you don’t repay.
- ASIC Moneysmart has a free payday-loan calculator and alternatives guide.
If you’ve weighed the cheaper options and a small short-term loan is still the right fit, you can apply below. We’ll pass your details to a licensed lender who assesses affordability and makes any decision. Applying is free and never guarantees approval.
Work out the legal maximum cost
See the most a payday loan (a Small Amount Credit Contract) can legally cost in Australia, capped at a 20% establishment fee plus a 4% monthly fee. This is an illustrative maximum: your actual rate depends on the licensed lender who assesses you.
Most it can legally cost
- Establishment fee (max 20%)$200
- Monthly fees (max 4% × 6)$240
- Maximum cost of credit$440
- Most you would repay$1,440
- ≈ per fortnight$111
- Annualised cost of those fees (APR-style estimate)≈ 147% p.a.
Illustrative only, capped by law. A Centrelink advance or a No Interest Loan (NILS) may cost $0 in fees. The annualised figure treats the capped fees as if they were interest on fortnightly repayments, so you can set it against a personal loan or credit card rate; a lender's published comparison rate is calculated under the National Credit Code on a set example and can be higher again.
Frequently asked questions
Can I get a loan while on Centrelink?
Yes. The cheapest routes are a Centrelink Advance Payment (interest-free) or a No Interest Loan (NILS). Some licensed payday lenders also accept Centrelink income, but at a much higher cost.
How much can I borrow from Centrelink directly?
Only an Advance Payment, and the amount depends on your payment type and circumstances. The '$10,000 from Centrelink' figure on some sites is misleading, because Centrelink itself doesn't lend that.
Is 'no credit check' or 'guaranteed approval' real?
No. Licensed lenders are legally required to assess affordability under responsible-lending law. Claims of guaranteed approval are a red flag, not a feature.
Can single parents or students on Centrelink get a loan?
Often, yes. Payment type matters more than most sites admit. Pensions and long-term payments (Age Pension, Disability Support Pension, Carer Payment, Parenting Payment) are the most widely accepted. Study and youth payments are the least: Money3, for example, publishes that it cannot consider Youth Allowance, Abstudy or Austudy. Criteria differ between lenders, so check before you apply rather than after a decline. But student and single-parent incomes are modest, so affordability is the real test. For essentials, an interest-free Centrelink Advance or a No Interest Loan (NILS) is almost always cheaper than a payday loan and worth checking first.
What if a lender treats me unfairly?
Every licensed lender must belong to the Australian Financial Complaints Authority (AFCA). You can complain free at afca.org.au or call 1800 931 678.
Can I get a loan on JobSeeker?
Some lenders count JobSeeker as income, but few will lend on JobSeeker alone because the payment is modest and expected to end when you find work. If JobSeeker is your only income, an interest-free Centrelink Advance Payment or a No Interest Loan will almost always be cheaper and easier to get than a payday loan.
What is the 50% Centrelink rule?
Many lenders, including Cash Converters and Nimble, only consider applicants who get less than half their income from Centrelink. It isn't a law, it's a lending policy, and some lenders don't apply it, but if benefits are all or most of your income you should expect fewer lenders to consider you.
Do lenders accept the Disability Support Pension?
The Disability Support Pension, along with the Age Pension and Carer Payment, is the most widely accepted Centrelink income because it's long-term and stable. The lender still has to check the repayments fit your budget, and for a DSP recipient the interest-free Advance Payment is usually the better first step.
How long does a Centrelink Advance Payment take?
You apply through myGov or the Express Plus Centrelink app, and the money usually arrives in your bank account within a few business days. Repayments then come off your regular payments automatically, typically over the following 13 fortnights.
Can I get a Centrelink loan for a car or a rental bond?
A No Interest Loan (NILS) covers up to $5,000 for an essential vehicle and up to $3,000 for a rental bond, with no interest and no fees, and it's open to anyone with a Health Care Card or Pensioner Concession Card. That beats any payday loan for those two purposes by a wide margin.